By James Mitchell
It has been a weird start to the fall for cattle markets. Tight cattle supplies continue to support prices, but unexpected policy changes have added uncertainty. The phased reopening of southern ports to Mexican cattle and a temporary increase in lean beef import quotas have been two main sources of uncertainty for cattle markets. Higher input costs and an August corn rally have also complicated things and added to this year’s volatility.
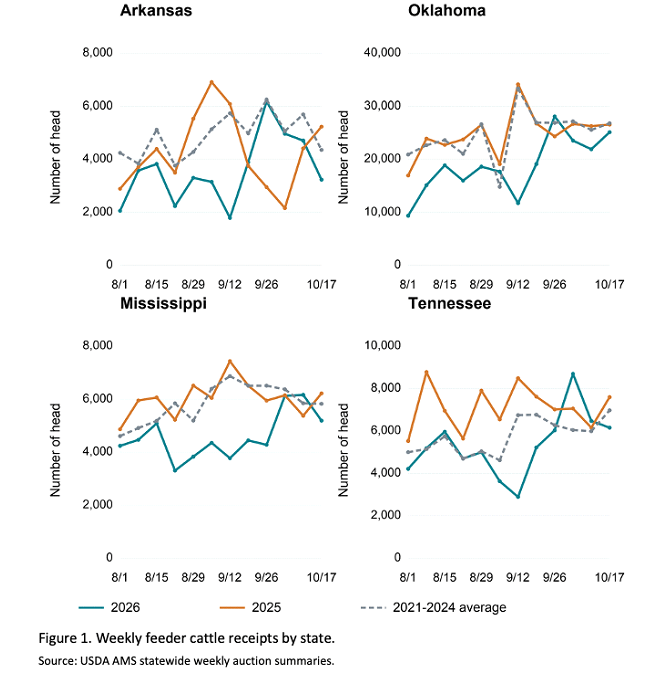
Drought has added another challenge for producers. Severe drought (USDM D2) or worse expanded across the southeast. Severe drought (USDM D2) or worse expanded in all four states between late July and mid-October. For example, in Arkansas, the share of the state in severe drought or worse increased from 21.9% on July 28 to 91.3% on October 13. Oklahoma increased from 35.0% to 79.6%, Mississippi from 8.2% to 37.3%, and Tennessee from less than 0.1% to 36.9%. The severity and timing of drought have also differed. On October 13, extreme drought (D3) or worse covered 65.4% of Arkansas and 43.8% of Oklahoma, compared with 9.6% of Mississippi and 7.5% of Tennessee.
Source : osu.edu